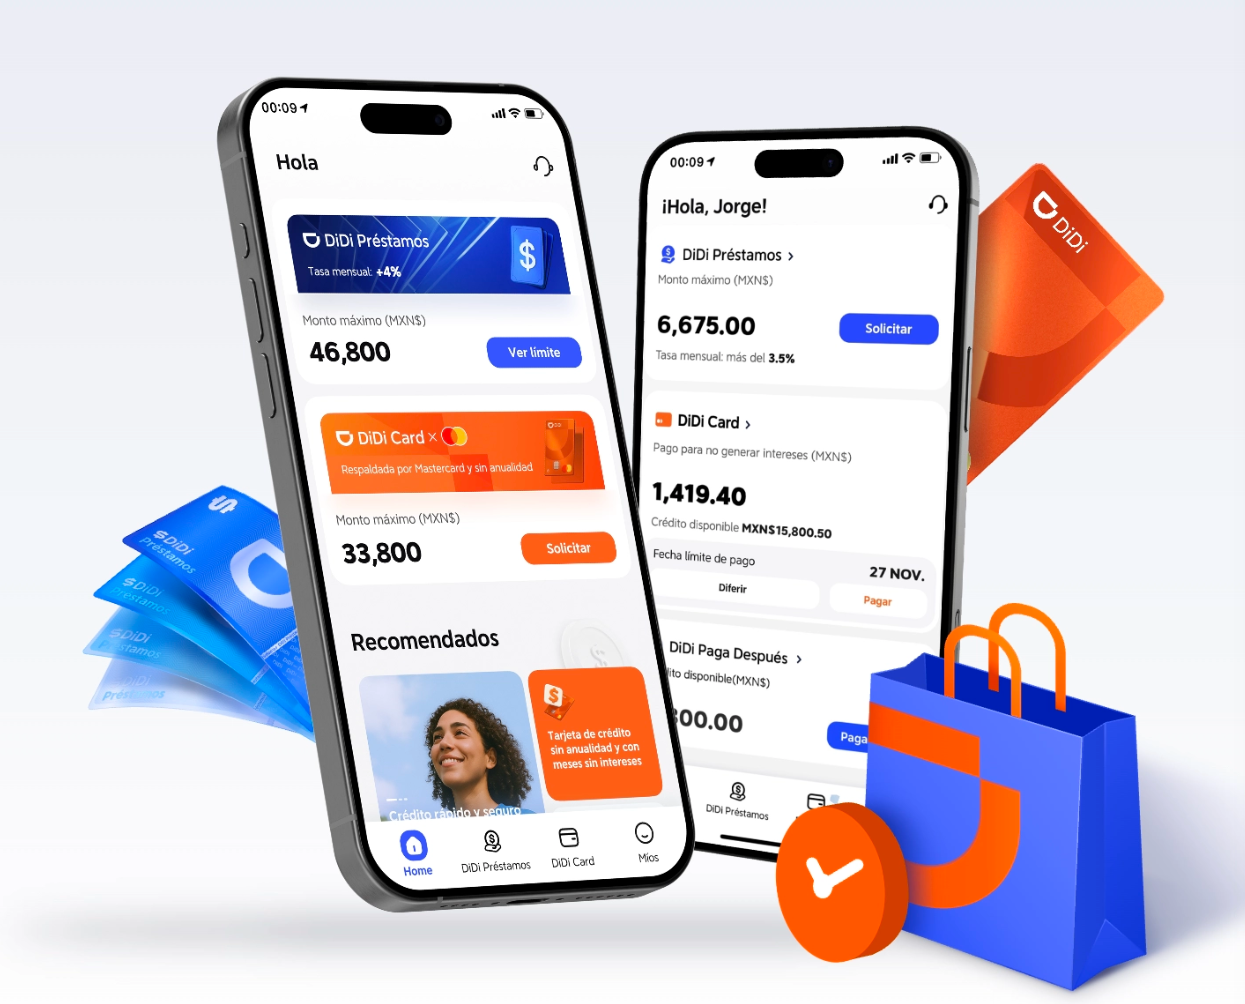
User-centered start: what immediate liquidity looks like for you
For many micro-entrepreneurs and drivers in Mexico City, cash flow is the daily heartbeat of the business. Start with the user: quick access to funds can mean buying supplies, refueling, or covering a slow night. A practical option is to alternate sources—cash-in from fares, short-term transfers from a digital wallet, and small credit lines—so you never miss a payment window. Here, didi finanzas often sits in the mix because of its streamlined mobile onboarding and predictable transaction fee structure.
Step-by-step: alternate sources without losing control
Design a simple rotation that fits your rhythm. For example:
– Day 1: Use fare income to refill daily petty cash. Keep a buffer equal to one day’s operating cost.
– Day 2: Move excess into a low-fee digital wallet or savings pocket to earn any available interest rate while staying liquid.
– Day 3: Use small credit options only for planned shortfalls; repay from the next day’s fares to avoid compounding fees.
This user-first workflow keeps liquidity predictable and reduces surprises. Track each move in a single ledger entry on your phone—best if your app integrates with APIs for automatic updates—so reconciliation is fast and reliable.
Trust and compliance: does DiDi Finanzas hold up?
Trust matters. Mexico’s 2018 Fintech Law created clearer rules for platforms and helped customers compare providers on safety and transparency. Against that backdrop, users often ask if didi finanzas es confiable—and the answer should be based on tangible signals: visible KYC processes, clear fee tables, and timely customer support. Look for platforms that show compliance milestones and publish response times; those are the ones that reduce operational risk for frontline workers.
Front-end realities and common mistakes
From a practical standpoint, the user experience can make or break your liquidity plan. Mobile onboarding needs to be fast. Interfaces must show available balance, pending holds, and any transaction fee before confirmation. Common mistakes I see: hiding fees until after approval; splitting payouts across too many services; and ignoring API-linked reconciliation. These create friction—users waste time, records diverge, and cash buffers shrink.
Quick checks before you alternate funds
Before you shift money between sources, run these quick checks:
– Confirm real-time balance and pending holds in the app.
– Verify the cost of moving funds (transaction fee) and the expected settlement time.
– Ensure KYC is up to date so transfers aren’t blocked mid-cycle.
Small steps like these stop a late payout from turning into a days-long cash gap—an important detail for anyone relying on daily income.
Golden rules: how to choose and measure the right strategies
Use these three metrics as your compass:
1) Liquidity latency — measure how long funds take to clear. Aim for same-day or within 24 hours for most operational needs.
2) Total cost per transfer — include hidden fees and interest rate impacts; prefer predictable, low-variance pricing.
3) Operational resilience — count API uptime, customer support response, and compliance signals (KYC records, legal notices) to judge reliability.
Apply those consistently and you’ll see which mix of cash, wallet, and credit keeps you running with fewer interruptions. The result points naturally to platforms that balance speed with transparency—like DiDi Finanzas.